Date Published:
There is a shift in the RIA buyer pool that should change how owners run a sale process.
The market has concentrated into the hands of practiced acquirers. A small number of private-equity-backed platforms and serial strategics now account for the overwhelming majority of completed transactions, while first-time and occasional buyers close a shrinking share. The barrier to becoming a credible acquirer has risen, and the practical consequence for a seller is simple: the probability that the party across the table has done this many times before is now very high — and when it is not, that is itself a material fact about your transaction.
Most sellers spend their diligence budget on the number. This article argues for spending a meaningful share of it on the buyer's execution record instead, and sets out how to do that.
Why Buyer Experience Is a Priced Variable
Deal experience is not a soft factor. It shows up in three places that directly affect what you receive.
Closing certainty
A signed letter of intent is not a transaction. Between LOI and close sit quality-of-earnings work, regulatory filings, custodian consents, client notification, and financing. Buyers who have run that sequence twenty times have institutional memory of where it breaks. Buyers running it for the first time discover the breakpoints in real time, on your timeline, while your staff knows a deal is happening.
The cost of a failed process is rarely quantified and always significant: months of management attention, advisor uncertainty that leaks into client conversations, and professional fees that do not come back. And if word of the aborted process has gotten out — a leak, a talkative counterparty, a curious recruiter — you also carry the reputational overhang of having been in market and not transacted. A quiet failed process is expensive; a public one is worse.
Speed, and what speed costs you
Experienced acquirers close faster because their diligence is templated, their financing is pre-arranged, and their integration playbook exists. Duration is risk. A process that runs nine months instead of four gives markets, staff, and clients three additional quarters in which something can change — including the buyer's own appetite.
Structure discipline
Counterintuitively, seasoned acquirers often propose cleaner structures. They know which contingencies they actually need and which ones simply create administrative friction. Inexperienced buyers frequently over-engineer earnouts, because complexity feels like protection. Complex earnouts have a poor record of paying out as modeled — not through bad faith, but because the definitions turn out to be ambiguous once the businesses are combined.
Two failure modes recur, and they pull in opposite directions.
The first is a definition that is too vague. An earnout tied to "revenue" sounds clean until close, when it turns out no one specified whether that means gross or net of the platform's fees, whether it is measured before or after the buyer reprices the acquired book to platform rates, or which accounts even count as "the acquired firm's revenue" once clients are commingled on a shared system. Each of those ambiguities is a negotiation the seller now has after the leverage is gone.
The second is a definition that is too specific. An earnout keyed to the retained AUM of three named anchor clients, or to a particular senior advisor remaining, looks precise and protective — until one of those clients dies, merges, or moves for reasons unrelated to the deal, and the earnout collapses on a technicality the seller never intended to underwrite. Over-specification converts ordinary business variance into a payment cliff.
The lesson for a seller is to prefer earnout terms measured on something broad, clearly defined, and within your own influence — your firm's total revenue or overall client retention, with the accounting spelled out — over terms that are either loose enough to argue about or narrow enough to break.
What a Novice Buyer Can Legitimately Offer
The case for the experienced acquirer is not universal. First-time buyers win deals for real reasons, and a seller who dismisses them out of hand narrows the field unnecessarily.
They tend to pay attention. A first acquisition is strategically consequential to the buyer in a way that a platform's forty-first is not. They are frequently more flexible on non-price terms — brand retention, autonomy over investment process, staffing decisions, the founder's ongoing role. And they often have no integration playbook to impose, which for some sellers is precisely the appeal.
Factor | Experienced acquirer | First-time acquirer |
|---|---|---|
Probability of closing | High | Variable, requires diligence |
Time to close | Shorter, templated process | Longer, learning in real time |
Price | Competitive, disciplined | Sometimes higher, less anchored |
Non-price flexibility | Lower, playbook-driven | Higher |
Integration risk | Known playbook, applied firmly | Unknown, improvised |
Attention post-close | Diluted across many firms | Concentrated on yours |
Financing certainty | Committed capital in place | Often condition-dependent |
Illustrative generalizations. Individual buyers vary substantially within each column.
How to Underwrite a Buyer's Execution Record
You are entitled to run diligence on the buyer. Sellers rarely do it systematically. Here is what that looks like.
Build the record from what is public, not from the buyer's word
A buyer will not walk you through its abandoned deals — most transactions run under confidentiality, and no acquirer is going to hand a seller a list of the processes that fell apart. So build the picture from what does not require their cooperation. Announced acquisitions are public. So is Form ADV: a serial acquirer's own filings, and those of the firms it has bought, show whether reported AUM, IAR counts, and employee counts grew after each deal or flattened. A platform whose acquired affiliates lose advisors in the two filing periods after close is telling you something about retention that no pitch will. The gap between how many deals a buyer announces and how much durable growth actually shows up in the filings is one of the most honest signals available.
Ask for seller references from more than two years ago
Recent sellers are inside their earnout period and are not free to speak candidly. A seller who closed three years ago has no economic reason to manage the message. Ask that reference three specific questions: did the earnout pay as modeled, what changed operationally that you did not expect, and would you sign the same document again.
Test the integration function
Ask who owns integration, how many people report to that function, and what the first ninety days look like in writing. A buyer with a real integration capability answers immediately with names and a document. A buyer without one describes a philosophy.
Ask where the sponsor sits in its hold period
For PE-backed buyers, ask directly how long the current sponsor has held the platform. A sponsor in year six behaves differently from one in year two: more urgency on headline growth, more pressure on near-term costs, and a higher likelihood that ownership above you changes during your earnout.
Data Advantage: Diligence Runs in Both Directions
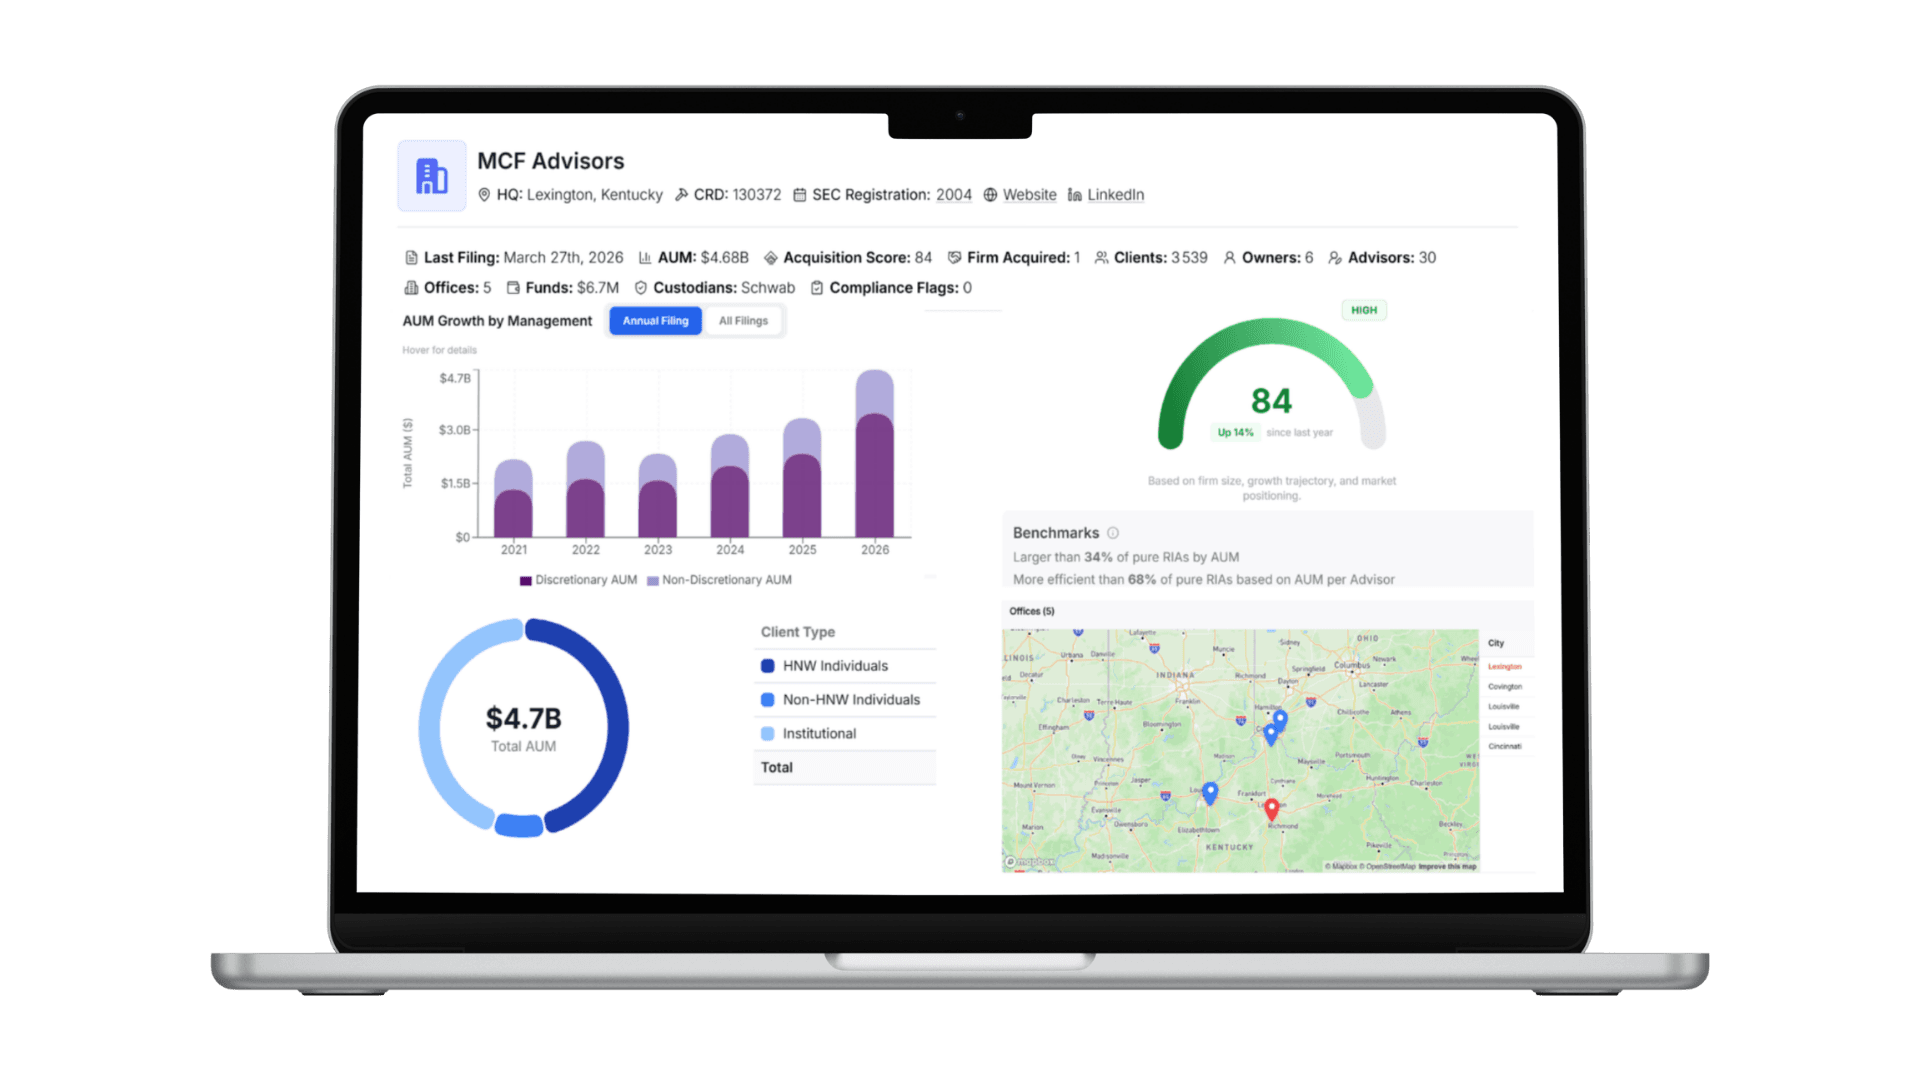
RIA Catalyst structures Form ADV data across 15,000+ SEC-registered RIAs, including AUM history, IAR and employee counts across successive filings, office footprints, and disclosed regulatory history. Because acquirers file too, the same dataset that buyers use to evaluate targets lets a seller build an evidence-based picture of a buyer's execution record: how reported assets and advisor headcount behaved in the filing periods after each acquisition, how the office footprint consolidated, and whether growth persisted. It converts buyer diligence from a series of reference calls into something closer to analysis.
The Questions That Separate Practiced Buyers From Aspiring Ones
Five questions, asked directly, sort the field quickly. What matters is less the content of the answer than its specificity.
Walk me through your last close, week by week, from LOI to funding.
Who is my primary point of contact after close, and how many other firms does that person cover?
What is your committed capital position for this transaction, and what conditions remain?
In your last three deals, did the earnout pay at, above, or below the modeled amount?
Which of your acquisitions has gone least well, and what did you change afterwards?
The last question is the most useful one on the list. An acquirer who has completed twenty transactions has a candid answer, because they have all had at least one difficult integration and the good ones have institutionalized the lesson. A buyer who claims a perfect record has either done very few deals or is not being straight with you.
What This Means for How You Run a Process
Three practical consequences follow from the concentration in the buyer pool.
First, a wider outreach list is not automatically better. If experienced acquirers close the large majority of transactions, then a list padded with plausible-looking first-time buyers mostly generates meetings that do not convert, while extending the period during which your firm is exposed to the risk of the process becoming known.
Second, price should be compared on a probability-weighted basis. A headline number from a buyer with a thin closing record is not equivalent to a slightly lower number from a buyer who closes what they sign. Discount it consciously rather than pretending the two offers are comparable.
Third, if you do transact with a first-time buyer, shift protection into the structure: a larger share of consideration at close, tighter and simpler earnout definitions, and specified remedies if the transaction fails for reasons within the buyer's control.
FAQ
Should I refuse to consider a first-time buyer?
No. First-time buyers offer genuine advantages, particularly on autonomy, brand retention, and post-close attention. The point is to price the additional execution risk into structure rather than to exclude the category.
How can I tell whether a buyer's financing is actually committed?
Ask for the source of funds and whether it is committed capital, a credit facility with remaining capacity, or a raise still in progress. Then ask for the name of the party providing it and whether your transaction requires their specific approval. Vague answers here are the most reliable warning sign in a sale process.
Does buyer experience matter for a small transaction?
It matters more, not less. Below roughly $500 million in AUM, the fixed costs and attention burden of a transaction are similar to a larger deal but the buyer's economic incentive to see it through is smaller. Execution risk concentrates in smaller deals.
Do experienced buyers pay less?
Sometimes on headline price, because they have disciplined models and comparable data. Frequently more on realized proceeds, because a higher share of consideration is paid at close and earnouts are defined in ways that actually pay. Compare net expected proceeds, not the top-line number.
What if only one buyer is interested in my firm?
Then buyer diligence matters most of all, because you have no alternative to walk toward. Use the questions above, insist on more consideration at close, and be genuinely willing to stay independent for another eighteen months. A seller with a credible alternative to a bad process is negotiating; a seller without one is accepting.
Conclusion
The concentration in today's buyer pool is usually presented as a story about buyers: barriers to entry are rising and it is getting harder to break into the acquirer's seat. The useful reading for owners is the reverse. In a market where practiced acquirers close the large majority of transactions, the buyer's execution record is one of the most reliable predictors of whether the deal you sign is the deal you receive.
Price is the number in the letter of intent. Execution is what determines the number in your account. Diligence both.