Date Published:
For most of the last decade, the premium narrative in RIA M&A pointed in one direction: up-market. Ultra-high-net-worth capability, family office services, alternatives access, tax and estate integration. The implicit message to owners serving households with $500,000 to $3 million was that they were in the wrong segment.
That message is now being contradicted by capital. Investcorp — a roughly $62 billion global alternative investment manager with no prior wealth-management holdings — made its first RIA investment by taking a majority stake in Berger Financial Group, a roughly $3 billion Minnesota-based firm founded in 1981 and employee-owned since 2018. The stated thesis was explicit: the mass-affluent client who needs financial advice, including first-generation wealth and families who have never worked with a planner. The plan involves expanding from five states and about ten offices to ten states and twenty-five locations.
That is not a defensive deal. Berger has grown through more than ten acquisitions and senior hires, and Investcorp described its intent as scaling that engine rather than harvesting the asset base. It is a growth thesis on a segment the market had largely written off as unattractive, and it arrives alongside a broader pattern — new institutional entrants, alternatives-focused and technology-forward platforms, and consolidators reporting that firms under $500 million still account for a large share of their acquisitions.
This article examines what changed, what buyers actually underwrite in a mass-affluent business, why the metrics differ from UHNW underwriting, and what owners in this segment should be building.
What Changed in the Underwriting
Three shifts made the segment investable.
The supply and demand imbalance moved down-market
The number of households needing financial advice has grown faster than the number of advisors serving them, and the imbalance is most severe below the UHNW threshold. Firms at the top of the market compete for a finite pool of very large relationships against private banks, multi-family offices, and each other. A firm serving mass-affluent households competes in a market where demand exceeds supply — which is a structurally better position for organic growth, and organic growth is what buyers pay premiums for.
Delivery cost fell enough to make the arithmetic work
The historical objection to mass-affluent was cost to serve. Planning-heavy service at moderate account sizes did not support a viable margin structure. That objection has weakened as planning software, automated portfolio management, model-based investing, and workflow tooling reduced the labor required per household. The segment did not become more lucrative per client; it became cheaper to serve enough clients.
The revenue base looks different, in a good way
A mass-affluent business built on many moderate relationships has a revenue base with different characteristics than one built on a handful of very large ones. Buyers evaluating recurring revenue durability read a broad base of households as a structurally more stable revenue profile than an equivalent amount of revenue concentrated in very few relationships. That is a valuation input, and one that ran against the segment when scale was the only thing being priced.
Why the Metrics Differ From UHNW Underwriting
The same headline AUM figure means something entirely different in the two segments, and the ratios buyers examine diverge accordingly.
Metric | Mass-affluent firm | UHNW firm |
|---|---|---|
Households per advisor | High, often several hundred | Low, often fewer than fifty |
Average relationship size | Moderate | Very large |
AUM per IAR | Driven by process and support bench | Driven by relationship depth |
AUM per total employee | The critical ratio | Less diagnostic |
Revenue durability driver | Breadth of household base | Depth of individual relationships |
Growth mechanism | Repeatable client acquisition | Referral and network access |
Key operational risk | Service model breaks under volume | Single relationship departure |
Integration difficulty | Lower, process-driven | Higher, relationship-driven |
Illustrative comparison of typical segment characteristics.
The most important line is AUM per total employee. In a UHNW firm, AUM per IAR is the headline productivity read, because value is concentrated in advisor relationships. In a mass-affluent firm, the business is a service delivery system, and its efficiency shows up across the whole employee base — including the non-IAR staff who do most of the client-facing work.
Illustrative example (hypothetical numbers only). Firm A is a mass-affluent business with $2.0B AUM, ten IARs, and forty-two total employees. AUM per IAR: $200M. AUM per employee: $47.6M. Firm B is a UHNW business with $2.0B AUM, ten IARs, and eighteen total employees. AUM per IAR: $200M. AUM per employee: $111M.
Identical AUM per IAR. Very different companies. Firm A has built a delivery organization in which non-IAR staff carry substantial client work — which is exactly what makes the mass-affluent model scale, and exactly why the AUM per IAR ratio alone tells a buyer almost nothing about it. The AUM per advisor figure counts only IARs registered on Form ADV, so a firm with a deep non-IAR bench looks efficient on that ratio while its total-employee ratio reveals the real cost structure.
What Buyers Underwrite in a Mass-Affluent Business
Whether the service model is a system or a set of habits
The central question. A firm serving several hundred households per advisor either has a documented, repeatable service calendar — defined touchpoints, standardized planning deliverables, tiered service levels — or it has senior people absorbing variability through effort. The first is an asset a buyer can extend across more households. The second breaks the moment volume increases or a key person leaves.
Whether client acquisition is repeatable
Mass-affluent economics depend on adding households continuously. Buyers want to see a defined acquisition channel that produces new relationships at a predictable rate — whether that is employer-sponsored plan relationships, professional referral networks, digital acquisition, or geographic density. A firm whose growth comes entirely from one founder's personal network is not a scalable mass-affluent business regardless of its current size.
Organic asset growth net of market appreciation is measurable from successive Form ADV filings, as is client count growth. The combination is telling: rising client count with rising assets indicates real acquisition; rising assets with flat client count indicates market beta and existing clients getting older and richer.
Whether the geographic footprint supports the model
The Berger plan — ten states, twenty-five locations — reflects something real about this segment. Mass-affluent service benefits from local presence and density in a way UHNW service does not. Buyers examine the office footprint on Form ADV and ask whether locations have enough advisors and households to be economically viable, or whether the firm has planted flags it cannot support.
Whether the technology investment already happened
Mass-affluent economics depend on tooling. A buyer arriving to find that the firm's efficiency comes from staff effort rather than systems is looking at a required investment, and required investment reduces price. A firm that has already made the investment is selling a working machine.
Data Advantage: Reading Segment Profile From Filings
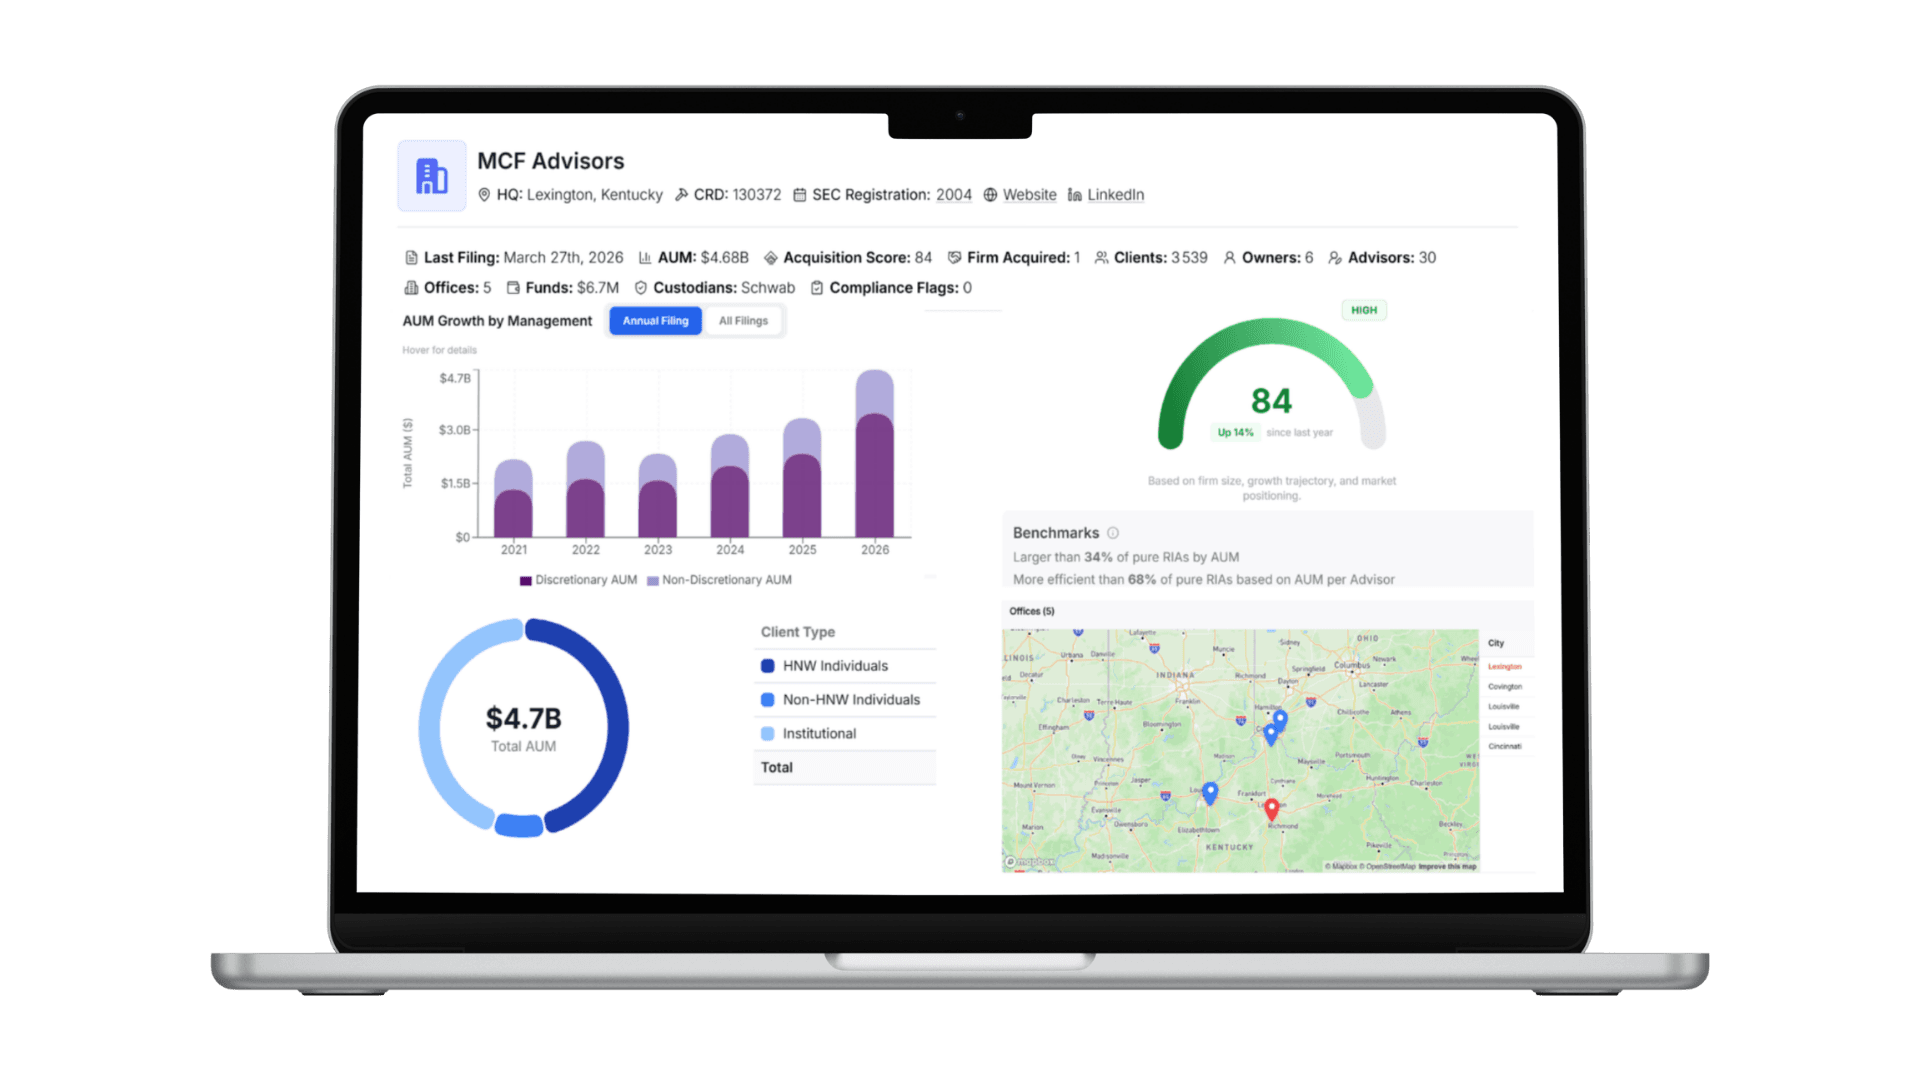
RIA Catalyst structures AUM, client and account counts, IAR counts, total employee counts, and office footprints across 15,000+ SEC-registered RIAs. That combination makes segment profile visible without a conversation: average relationship size derived from assets and client counts, the ratio of IARs to total employees that distinguishes a delivery organization from a relationship-led practice, and the office density that indicates whether a geographic strategy is working. For acquirers building a thesis in this segment, and for owners benchmarking their own model against the firms attracting capital, the distinguishing characteristics are in the filings before they are in the pitch.
What Owners in This Segment Should Build
Five priorities, in order of impact on valuation.
Document the service model. Written service standards by client tier, with defined deliverables and frequencies. This is the difference between selling a system and selling your own capacity.
Widen the non-IAR bench deliberately. Client service, operations, and planning support are what make the model scale. A buyer reads a thin non-IAR bench relative to household count as capacity risk, not efficiency.
Prove one acquisition channel works. One documented, repeatable channel producing a measurable number of new households per year is worth more than three informal sources of referral. Track it and be able to state the number.
Get relationships off the founder. In a high-household-count firm this is more achievable than in UHNW, because the service model can genuinely own the relationship. Use that advantage: standardize who covers whom and make the firm the relationship holder.
File consistently. Client counts, account counts, and employee counts on Form ADV are the primary external evidence of your model. Inconsistent reporting across filings makes the growth story impossible to verify and invites the less favorable interpretation.
FAQ
Is the mass-affluent segment actually valued at a lower multiple than UHNW?
Historically yes, and the gap has narrowed rather than closed. What has changed is that the discount is now applied to the operating model rather than to the segment itself. A mass-affluent firm with a documented service system, a proven acquisition channel, and a real non-IAR bench can price competitively with a UHNW firm of similar size and growth. One dependent on founder effort cannot.
What household size defines "mass affluent"?
There is no standard definition. Practically, most buyers use it to describe households with investable assets roughly between $250,000 and $3 million. The more useful boundary is operational: mass affluent is where the service model does the work, and UHNW is where the individual advisor does.
Does a broad household base help or hurt valuation?
It generally helps, because a revenue base spread across many relationships is less exposed to the departure of any single one. The offsetting concern is service capacity: a large household count with a thin support bench is a risk, not a strength.
Should a mass-affluent firm try to move up-market before selling?
Rarely. Firms attempting the shift usually end up with two service models, neither executed well, and a story a buyer cannot underwrite. Depth in one segment is worth more than partial presence in two. The capital now entering this segment is buying mass-affluent execution, not aspiration.
Are technology-forward platforms competing for the same firms?
Increasingly, yes. Technology-led platforms and new institutional entrants are both underwriting the same thesis — that mass-affluent advice can be delivered profitably at scale. For owners, that means more buyer competition in a segment that recently had little, which is the most favorable condition a seller can face.
Conclusion
The Investcorp-Berger transaction is worth attention less for its size than for its direction. A large global investor chose a $3 billion firm serving mass-affluent households as its first entry into wealth management, with an explicit plan to expand the footprint rather than harvest the asset base.
For owners in this segment, the practical implication is that the discount is no longer assumed. It is applied to firms whose efficiency rests on effort rather than on systems. The firms attracting this capital have documented service models, deep non-IAR benches, proven acquisition channels, and technology already paid for. Those four things are what convert a mass-affluent practice into a mass-affluent business, and they are all buildable well before a process starts.