Date Published:

The loudest RIA transactions are control deals. A consolidator buys a firm, the firm’s brand disappears into a platform, and the AUM shows up in someone else’s press release. That is the version of the market most people track.
It is not the only version, and the quieter one is growing faster than its share of headlines suggests.
On August 25, 2026, Confluence Financial Partners — a Pittsburgh-based RIA overseeing roughly $7.6 billion, plus about $400 million in administered 401(k) plan assets — announced a minority investment from Constellation Wealth Capital, an alternative asset manager that specializes in minority, non-controlling investments in independent wealth management firms. Confluence’s founding leadership retains day-to-day control and long-term strategic direction. The sponsor is one of the more active dedicated minority investors in the space, having backed a series of growing independent RIAs — several of which have gone on to become acquirers themselves.
That is the shape of the structure: capital and resources in, control stays put, and the recipient firm frequently converts from potential seller into competing buyer. For anyone building an acquisition pipeline, this is not a niche financing story. It changes who is in the market, what they can pay, and how a target’s cap table should be read.
What a Minority Recapitalization Actually Does
A non-control investment typically delivers four things that a founder-owned RIA cannot easily generate on its own.
Liquidity without exit. Founders monetize part of their equity while continuing to operate the firm. This is the single most important effect: it removes the financial urgency that used to drive founders to a full sale.
Acquisition currency. Capital that would otherwise have to come from bank debt or seller notes becomes available for bolt-on deals. Firms that took minority capital eighteen months ago are announcing acquisitions now.
Institutional infrastructure. Sponsors bring recruiting support, technology roadmaps, M&A advisory, and — crucially — the credibility a sub-$10B firm needs to compete for advisor teams against $100B platforms.
Valuation reset. A minority round establishes a reference price. That number becomes the floor in every subsequent conversation, whether the sponsor intended it that way or not.
The trade is real. The founder gives up a share of future appreciation, accepts governance rights they did not previously have, and takes on an investor with a defined time horizon. But compared with a control sale, the founder keeps the thing they usually say they care most about: the ability to decide.
How This Changes the Competitive Map for Acquirers
The Seller Pool Shrinks at the Top End
Every high-quality firm that takes minority capital is a firm that has just told the market it is not selling control for several years. In a market already running at record deal volume, where the supply of genuinely attractive independent firms was the binding constraint, non-control capital tightens that supply further.
The practical consequence for a control buyer: the firms most likely to be recapitalized are the ones you most want, and the recapitalization typically happens before you get a serious conversation. Sourcing earlier is not a preference. It is the only response available.
The Buyer Pool Widens in the Middle
At the same time, the middle of the market gains a cohort of newly capitalized acquirers. A $5–10B RIA with a sponsor behind it can now compete for the same $300M–$1B tuck-in that a $60B consolidator wants, and can often offer something the consolidator cannot: a smaller platform where the seller’s team remains visible.
This is why the “we only compete against the big platforms” assumption is now wrong. The competitive set for a mid-sized target includes a growing group of firms that were themselves targets two years ago.
Pricing Gets Less Uniform, Not More
Different capital structures produce different offers for the same firm. That is not new, but the range has widened.
Buyer type | Control taken | Typical currency | What the seller keeps | Where it wins |
|---|---|---|---|---|
Majority PE-backed consolidator | Full | Cash plus platform equity | Compensation and a role | Highest headline number, deepest resources |
Minority-backed regional RIA | Full or partial | Cash, equity, seller notes | Brand, autonomy, local identity | Sellers who fear disappearing |
Non-control sponsor (direct) | None | Cash for a stake | Control and the franchise | Founders not ready to exit |
Strategic RIA, unsponsored | Full | Cash plus notes | Cultural continuity | Slower, cleaner processes |
Bank or insurance acquirer | Full | Cash | Little operational autonomy | Distribution and balance sheet |
A seller who understands this table runs a very different process from one who does not. A buyer who understands it stops assuming that the highest bidder wins.
Reading a Non-Control Investor on a Target’s Cap Table
Sooner or later a buyer will look at a target that already has a minority sponsor. Curi Capital’s transaction this week is the illustration: the $14 billion Chicago-based firm agreed to a new majority investment from Vistria, and Wealth Partners Capital Group — which had taken a minority stake in March — is expected to remain alongside the incoming majority owner and the firm’s employees. Non-control positions do not necessarily clear when control changes hands.
What that means in practice:
Governance rights outlive ownership percentage. A 20% holder may hold consent rights over acquisitions, debt, key hires, or a subsequent sale. The percentage tells you very little; the shareholders’ agreement tells you everything.
Timelines may already be running. A sponsor three years into a five-year hold has a different appetite for a transaction than one that invested last quarter. This is knowable from public reporting and it materially affects deal speed.
Price expectations are anchored. The minority round set a reference valuation. A control offer that does not clear it comfortably will struggle regardless of merit.
The seller may not be able to sell. Drag-along and tag-along mechanics, plus consent thresholds, mean the founder you are negotiating with may not control the outcome. Establishing who actually has authority to sign is a first-meeting question, not a diligence-phase question.
Data Advantage: Spotting Capital Events Before the Press Release
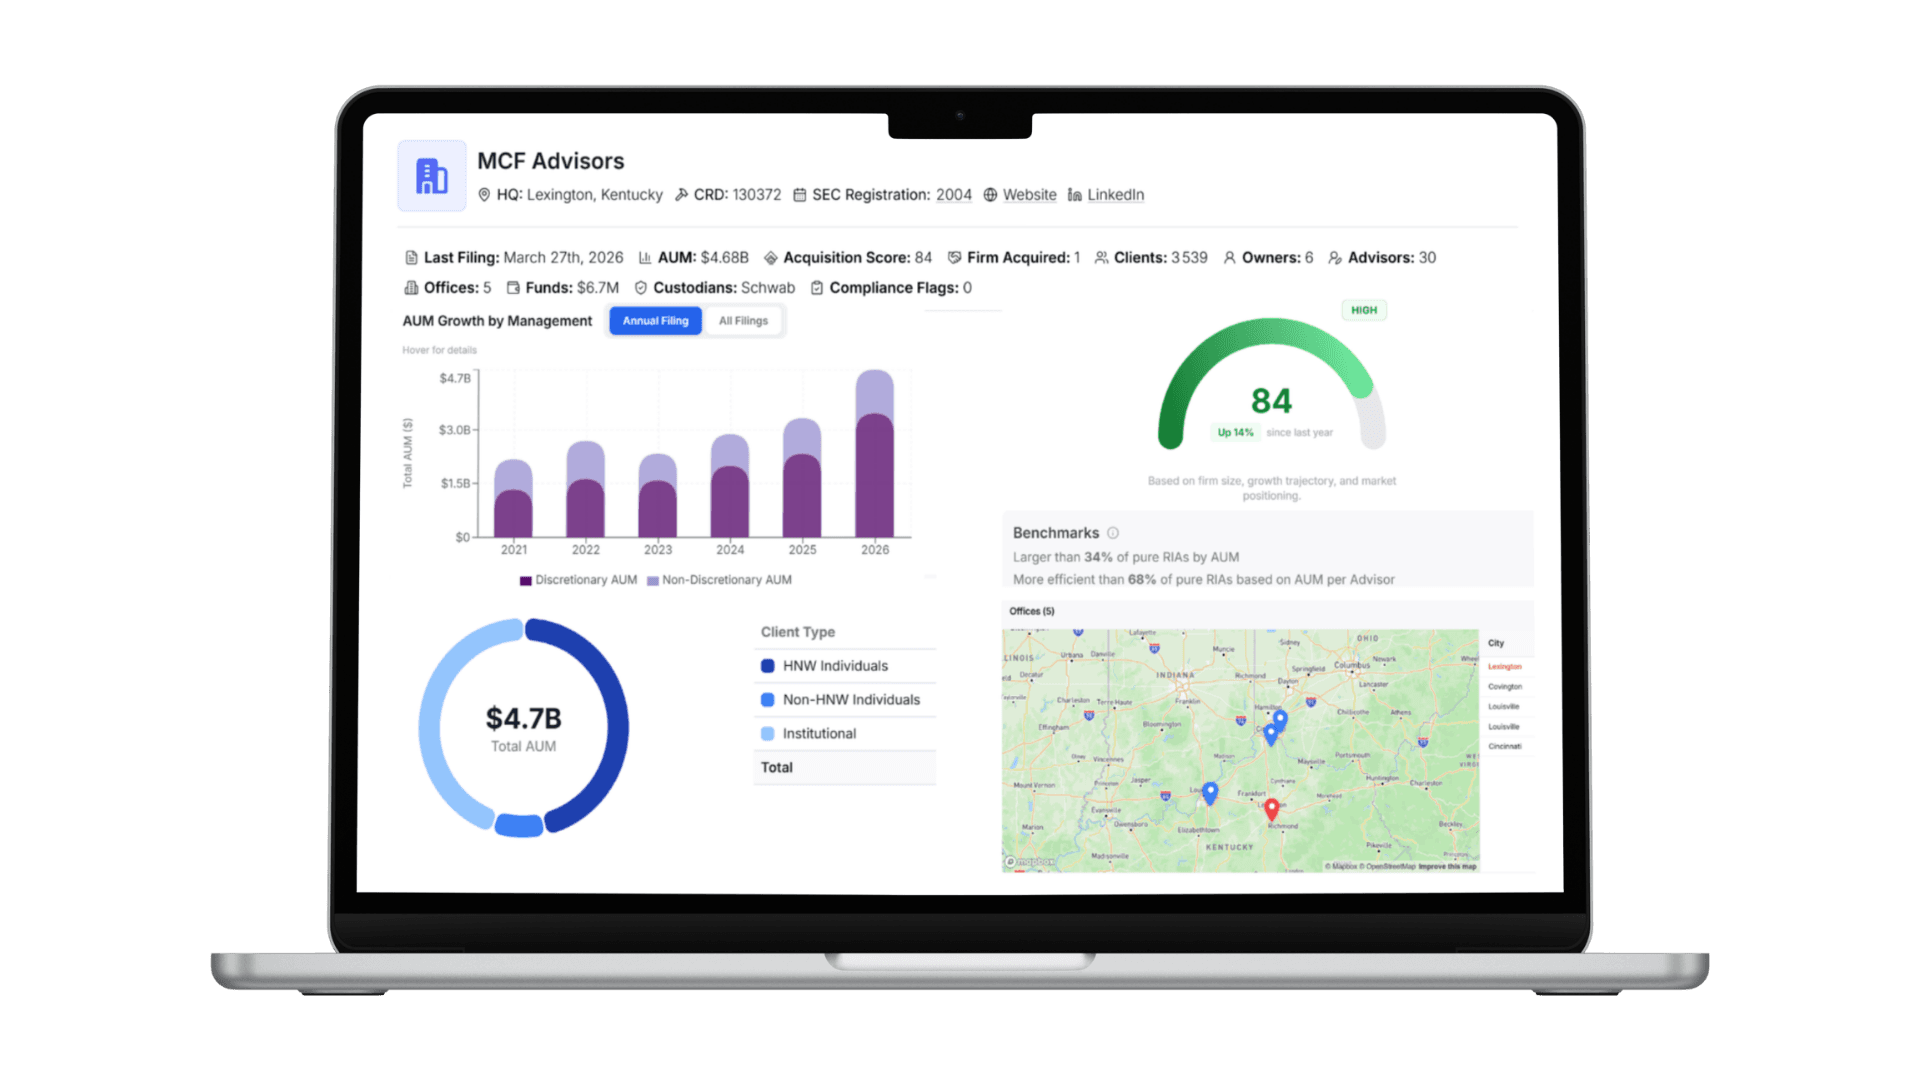
Ownership changes leave traces in public filings before they reach the trade press. RIA Catalyst tracks Form ADV data across 15,000+ SEC-registered RIAs, including direct and indirect owner disclosures, control-person changes, and the filing-over-filing shifts in AUM, IAR count, and employee count that typically precede or follow a capital event. Buyers monitoring a defined target universe can see when a firm’s ownership structure or growth trajectory changes — and can time an approach to the window before a sponsor process starts rather than after it closes.
What This Means If You Are the One Being Approached
For a founder-led firm, the arrival of non-control capital as a mainstream option changes the question from when do I sell to what am I solving for.
Consider two firms with identical economics (illustrative numbers only):
Firm A: $1.2B AUM, seven IARs, nineteen total employees. AUM per advisor: $171M. AUM per employee: $63.2M. At 0.70%, revenue of roughly $8.4M. Founder is 58, has two next-generation partners, and wants the firm to exist in twenty years.
Firm B: Same AUM, same headcount, same revenue. Founder is 66, has no internal successor, and wants a defined end date.
Firm A’s problem is capital and capability — exactly what a minority round supplies. Firm B’s problem is succession, and no amount of minority capital solves it; a control transaction does. The two firms will appear identical on a buyer’s screen and should reach completely different conclusions.
The failure mode is running the wrong process for your own situation because the wrong process is the one everyone talks about.
FAQ
Is a minority investment just a delayed sale?
Sometimes, but not by design. Sponsors in this segment typically underwrite growth over a multi-year hold and expect the firm to become an acquirer. Some of those firms will eventually sell control; others will recapitalize again or transition internally. Treating every minority round as a pre-sale signal will cause a buyer to waste outreach on firms that have just deliberately removed themselves from the market.
Do minority stakes command different valuations than control deals?
They are priced differently because they carry no control premium and no control obligations. Comparing a minority round’s implied valuation directly against control-deal multiples is not an apples-to-apples exercise, and sellers who do it in negotiation tend to anchor on the wrong number.
Are minority investments moving down-market?
Yes. The available industry evidence indicates minority investments in RIAs have been shifting toward smaller firms. That matters for buyers because it means the recapitalization dynamic now touches the $500M–$3B band, not just multi-billion platforms — precisely the band most tuck-in strategies target.
Can you tell from Form ADV whether a firm has taken minority capital?
Often, yes, indirectly. Schedule A and Schedule B disclose direct and indirect owners in bracketed ownership ranges, and a new institutional entity appearing between filings is a strong signal. The filing will not disclose deal terms, governance rights, or valuation — but it will tell you the cap table changed and roughly when.
If a target already has a sponsor, is it worth pursuing?
Yes, with different preparation. You are negotiating with a professional counterparty who has a valuation reference, a hold-period clock, and defined consent rights. Deals like these can move faster than founder-only processes because the seller side is institutionally decisive. What they will not do is move cheaply.
Conclusion
The minority-stake model has quietly changed the structure of the RIA market. It removes attractive firms from the control-sale pool, converts former targets into funded acquirers, widens the range of credible offers a seller can generate, and adds a professional counterparty to cap tables that used to contain only founders.
None of that is visible if you track deal announcements alone. It is visible in ownership disclosures, in growth trajectories, and in which firms suddenly start hiring and buying. Buyers who monitor those signals will see the market reorganize around them. Buyers who wait for the press release will keep finding out that the firm they wanted took someone else’s capital eight months ago.